Chapter 2 - The Silent Severance
The hum of the espresso machine at Panera Bread provided a rhythmic counterpoint to the quiet devastation inside my head. Outside, the night sky over Columbus, Ohio, was a deep, bruised purple, heavy with the promise of more snow. Inside, the warm air smelled of toasted yeast, cinnamon, and the crisp, clean scent of paper cups.
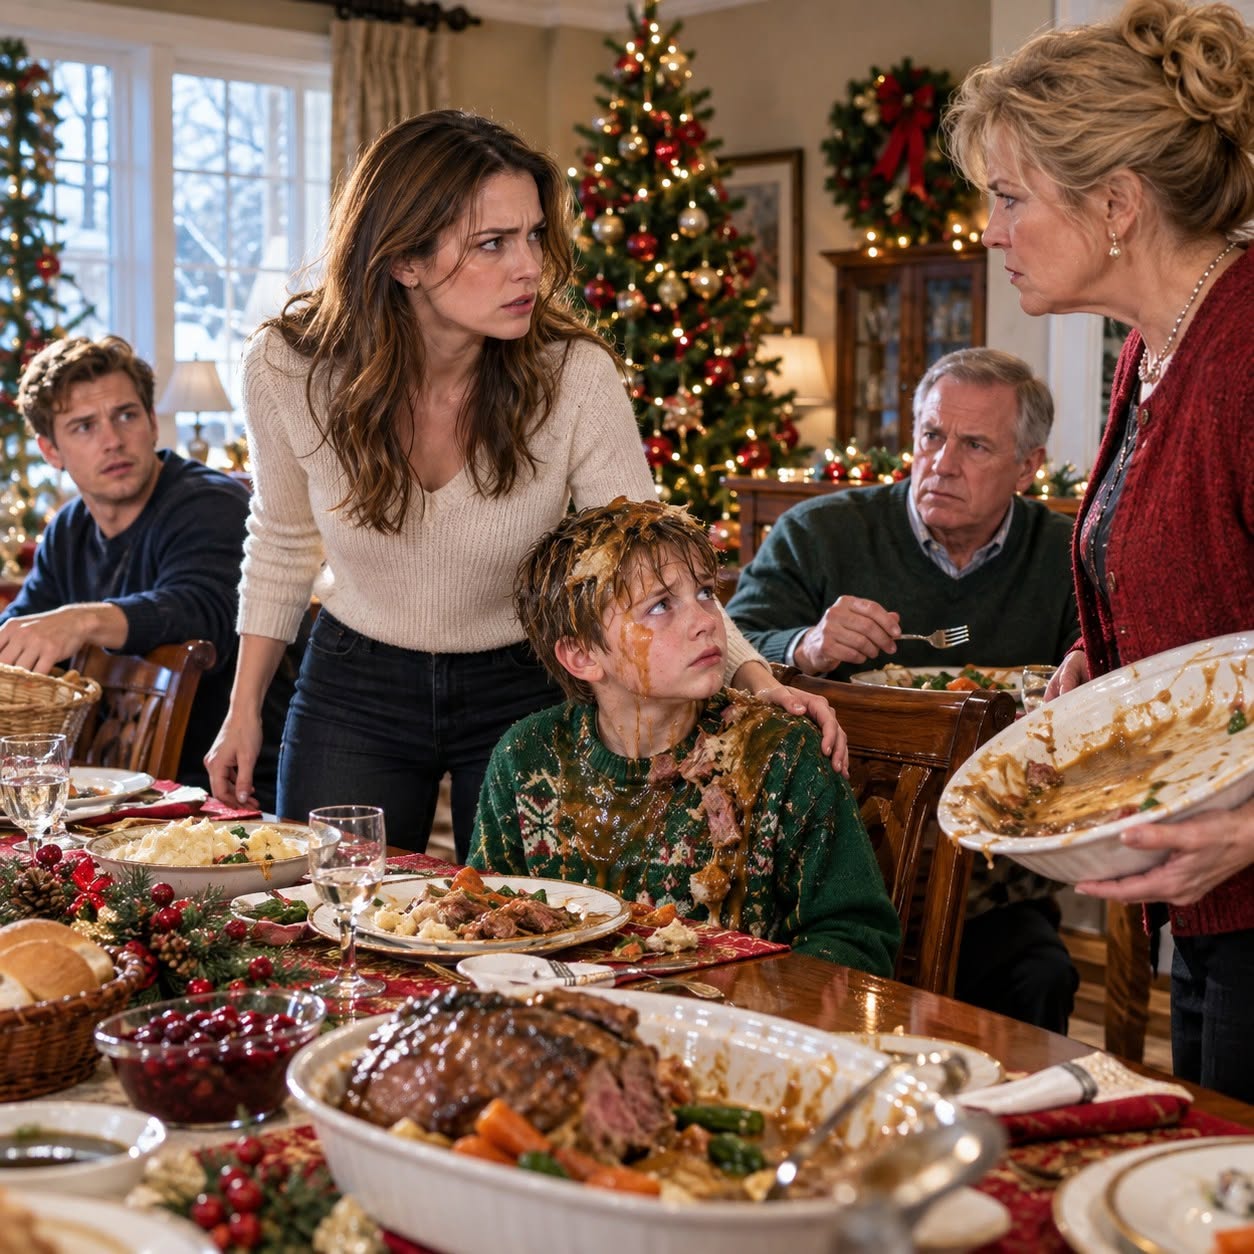
Across the wooden booth, nine-year-old Micah was carefully using his plastic fork to nudge a speck of cream cheese frosting toward the center of his cinnamon roll. His green sweater—the one I’d chosen with such quiet pride three weeks ago—hung over the back of his chair, a stiff, dark brown wreck of dried gravy and fat. He was wearing his backup zip-up fleece, two sizes too big, which I’d pulled from the trunk of my car.
He hadn’t mentioned his grandmother. He hadn’t mentioned the plate. He was existing in that hyper-vigilant, ultra-quiet state that children of unpredictable adults enter when they know the ground beneath them has cracked.
“Mom?” he said softly, his small voice barely cutting through the ambient noise of the café.
“Yeah, sweetie?”
“Is my train still in the car?”
“It’s right in the trunk, Micah. Safe and sound.”
He nodded once, satisfied, and took a small, careful bite of his pastry. He was nine years old, and he was already an expert at managing the emotional weather of the adults around him.
My phone sat face down on the laminate table. It didn’t vibrate. It didn’t ring. My mother had thrown us out, my father had gone back to his roast beef, and my brother had reached for the bread basket. In their mind, the scene was over. The unruly daughter and her strange, quiet child had been dismissed. I would drive home, cry, wash the sweater, and by Monday morning, I would transfer the funds to keep their lives from falling apart, just as I had every month for forty-eight months.
I reached out and turned the phone face up.
The screen lit up with the blue-and-white interface of my primary banking application. My thumb was steady. My heart rate, which had been racing at a hundred beats a minute in my parents’ driveway, had dropped into a cold, icy slow rhythm.
I tapped Transfers & Payments.
For four years, this screen had been my quiet altar of self-sacrifice. I had rationalized every single line item. My father’s contracting business, Vance & Sons Construction, had collapsed during the 2021 lumber spike and residential slow-down. He was fifty-nine then, too proud to take a foreman position with another company, too stubborn to file for business restructuring. He had simply stopped paying the mortgage on the four-bedroom colonial in Worthington where my brother and I had grown up.
When the first default notice arrived in the summer of 2021, I was twenty-seven. I was working sixty hours a week as a mid-level logistics manager for a regional distribution firm, saving every spare dollar for a down payment on a modest starter home for Micah and me. My father had stood in my cramped apartment kitchen, his hands rough from forty years of framing timber, looking down at his boots.
“It’s just six months, Clara,” he had said, his voice thick with a fake, forced shame that I now recognized as purely performative. “Just until the commercial bids come back in the spring. I can’t let your mother lose this house. It’s all she has.”
Six months had turned into a year. A year had turned into four.
I scrolled down to the first recurring payment: Union Savings & Loan — Mortgage Draft: $1,412.00 — Scheduled for Dec 28.
I pressed the small red button: Cancel Auto-Pay.
A dialog box popped up: Canceling this automated transaction may result in late fees or loan default if alternative payment arrangements are not made. Do you wish to proceed?
I tapped Yes.
Next was Apex Financial Auto Loan — $418.00 — Scheduled for Dec 30.
This was Ross’s 2022 Nissan Altima. When Ross came back from Chicago in late 2022 after what he vaguely called a "bad business partnership," he had no job, no credit score, and an eviction on his record. My mother had cried at the dinner table until I agreed to put the auto loan in my name so he could "drive to interviews." He had held three different jobs in twenty-four months, quitting each one because the supervisors were "idiots" or the hours interfered with his "life balance." For sixteen months, I had made every single car payment.
I tapped Cancel Auto-Pay.
I opened the bill-pay section. Columbia Gas of Ohio and AEP Power. Both were set to pull directly from my checking account on the first of every month. I unlinked my debit card, deleted my routing number, and removed myself as an authorized third-party payer.
Finally, I pulled up the First Horizon Bank Home Equity Line of Credit.
This was the $35,000 credit line my father had taken out in late 2022 to "upgrade" their kitchen with granite countertops and stainless-steel appliances—a project he claimed would raise the home's appraisal value so he could refinance and pay me back. I had co-signed the line because the bank refused to extend credit to a man with two active liens on his business account.
I couldn't unilaterally remove myself as a co-signer from a line of credit—that required legal intervention. But I could stop funding the monthly interest payments.
I cleared the auto-draft schedule.
In less than three minutes, I pulled $2,450 a month out of the foundation of my parents’ life.
I laid the phone back on the table.
Micah looked up, a thin smear of white icing on his upper lip. “Mom? Are you mad?”
May you like
I looked at my son—really looked at him. The gray-green eyes that looked so much like mine, the slight scatter of freckles across his nose, the absolute innocence of a boy who had spent his entire Christmas Eve afternoon being proud of a four-inch model steam engine.
“No, Micah,” I said, and for the first time in four years, my voice felt entirely my own. “I’m not mad at all. I’m finally awake.”